


How an annuity works
You provide a lump sum from your super to a life company or annuity provider. In return they guarantee to pay you a regular income – for example monthly or annually.
That income can last:
- For life (a lifetime annuity), or
- For a set number of years (a term annuity), or
- For life with a guaranteed minimum period (e.g. at least 10 years).
Why choose an annuity?
Guaranteed income
- Payments are predictable and stable
- No impact of market ups and downs
Funded by your super
- Super savings used to create a regular income
- Usually purchased at or after retirement
Built in protection options
- Indexation helps keep pace with inflation
- Reversionary benefits protect loved ones
Things to consider with an annuity
Income payment limitations
- Difficult to change the annuity terms once started
- Limited ability to vary income payments
Capital access restrictions
- Limited access to capital after purchase
- Cannot usually withdraw a lump sum for unexpected expenses
Limited investment growth
- Limited exposure to investment market gains or losses
- Focus on income certainty over capital growth

Is an annuity right for you?
- Retirees who value certainty over flexibility
- People worried about outliving their savings
- Those wanting a “base level” of guaranteed income to cover essentials
While annuities can provide certainty of income, they may offer less flexibility and access to capital than other retirement income options.
How can an annuity affect your Age Pension?
Some lifetime annuities may receive favourable treatment under Centrelink's assets and income tests. Eligibility and outcomes depend on your circumstances and the specific product. You should check the current rules and consider seeking financial advice.
Case Study: Using an annuity alongside an account-based pension
| A powerful retirement combination |
|
It is common when people move into retirement that they move all their accrued super into an account-based pension.
A pension account allows you to keep investing your capital to achieve growth and provides the flexibility of making tax-free withdrawals when needed. Yet, due to market fluctuations, investment returns can vary over time and are not guaranteed.
Allocating a portion of your savings into a separate lifetime annuity account, alongside your pension account, can add an extra layer of security to your retirement by providing you with a guaranteed income stream for life regardless of investment market movement.
Over time, as your account-based pension balance declines, and depending on your individual financial circumstances, you may also become eligible for government Age Pension payments in addition to your guaranteed lifetime annuity income.
The chart below illustrates how the combination of an account-based pension, a lifetime annuity, and the Age Pension can help achieve a resilient retirement strategy providing income certainty for life. |
A three-pillar retirement income strategy
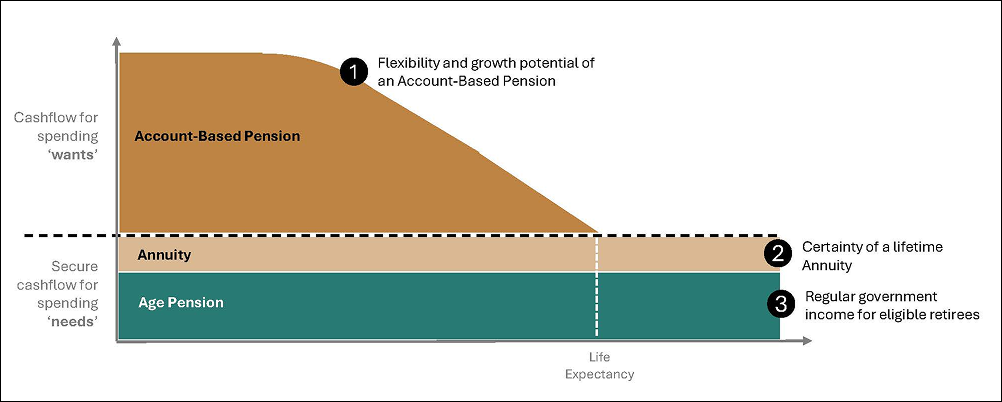
Note: The chart is for illustrative purposes only and is not intended as personal financial advice. Consider consulting a licensed financial adviser to assess your personal circumstances.
Account-based pension can commence after meeting a condition of release (commonly age 60+ or age 65); an annuity can commence once funds are available and, if using super, after meeting a condition of release; and age pension can commence at age 67 subject to eligibility.
Source: legalsuper
Want to learn more or purchase an annuity?
legalsuper is not a provider of annuity products. However, there are a range of providers available to purchase annuities. One example is Challenger who is an established provider of retirement annuity products in Australia. If you would like to contact Challenger, you can visit their website www.challenger.com.au or call them on 13 35 66.
legalsuper does not recommend or endorse Challenger or any other annuity provider and does not receive any remuneration or other benefit from Challenger. Any references to Challenger are provided for general information only.
This information is general in nature and does not take into account your personal circumstances. Retirement income products, including annuities, can be complex and may have long‑term implications. You should consider seeking advice from a licensed financial adviser before making any decision.